Growth is usually seen as a sign that a business is doing well.
Sales are increasing. New customers are coming in. More employees are being hired. Larger orders are being placed.
But there is a problem many growing businesses discover:
More sales do not always mean more cash in the bank.
In fact, a rapidly growing business can experience more cash flow pressure than a stable business.
You may need to pay employees, suppliers, superannuation, rent, tax and other operating expenses weeks before your customers pay you.
This is where a 13-week cash flow forecast can become one of the most valuable financial management tools available to a growing business, and a core part of good management reporting.
What Is a 13-Week Cash Flow Forecast?
A 13-week cash flow forecast estimates the cash expected to come into and leave your business each week for approximately the next three months.
Unlike a Profit & Loss report, which tells you about profitability, a cash flow forecast focuses on a different question:
Will we have enough cash available to meet our upcoming commitments?
A typical 13-week forecast starts with your current bank balance and considers expected cash movements such as:
Cash coming in:
- Customer receipts
- Cash sales
- Other operating income
- Loans or funding
- Other expected cash inflows
Cash going out:
- Supplier payments
- Wages
- Superannuation
- PAYG withholding
- BAS and tax payments
- Rent
- Loan repayments
- Insurance
- Inventory purchases
- Equipment and capital expenditure
- Other operating costs
The result is an estimated closing cash balance for each of the next 13 weeks.
Why 13 Weeks?
Why not forecast for six months or twelve months?
Annual budgets and longer-term forecasts are extremely useful for strategic planning, but they serve a different purpose.
A 13-week forecast provides a much more detailed view of short-term liquidity.
Thirteen weeks is roughly one quarter.
That is generally far enough ahead to identify potential cash pressure while remaining close enough to make reasonably informed assumptions about customer receipts and upcoming payments.
It can help answer questions such as:
- Will we have enough cash for payroll next month?
- Can we comfortably pay the upcoming BAS?
- Can we afford to hire another employee?
- What happens if our largest customer pays two weeks late?
- Can we purchase new equipment now?
- Do we need additional working capital?
- Are we likely to experience a cash shortage in the next three months?
These are very different questions from simply asking whether the business will make a profit this year.
Why Growing Businesses Need Cash Flow Forecasting
Growth can create significant demands on working capital.
Imagine your business wins several large new customers.
That sounds fantastic.
But to service those customers, you may need to:
- Hire additional employees
- Purchase more stock
- Increase supplier orders
- Invest in equipment
- Increase marketing expenditure
- Pay additional freight
- Move into larger premises
Those expenses may need to be paid before your customers pay you.
The business can therefore become more profitable while simultaneously becoming more cash constrained.
This is sometimes referred to as overtrading — where a business grows faster than its available working capital can comfortably support.
A 13-week cash flow forecast can help management identify that pressure before it becomes critical.
Profit Does Not Equal Cash
This is one of the most important concepts for business owners to understand.
Your Profit & Loss statement might show:
Profit: $250,000
But that does not mean there should be $250,000 sitting in the bank.
Cash may have been used to:
- Purchase inventory
- Repay loans
- Purchase equipment
- Fund customer debtors
- Pay tax liabilities
- Make owner drawings or distributions
- Make deposits or prepayments
- Fund business expansion
This is why a business owner can genuinely say:
“We are profitable, but I never seem to have enough cash in the bank.”
A 13-week forecast helps bridge the gap between accounting profit and actual cash availability. If you are not sure which figures to watch first, see our guide on 5 key numbers to review monthly.
When Should Your Business Prepare a 13-Week Forecast?
There are several situations where we believe a short-term cash flow forecast becomes particularly valuable.
1. Your Business Is Growing Quickly
Rapid growth is one of the strongest reasons to introduce regular cash flow forecasting.
If sales are increasing significantly, your expenses and working capital requirements may increase before the additional cash is collected.
A forecast helps you assess whether your existing cash reserves can support the growth.
2. Customers Are Taking Longer to Pay
Revenue on your Profit & Loss does not necessarily mean money in your bank account.
If customers take 30, 45 or 60 days to pay, the business may have to fund expenses during that period. Tighter accounts receivable follow-up can shorten that gap.
Your forecast should therefore be based on when you realistically expect customers to pay, rather than simply when invoices are issued.
3. You Have Large Upcoming Tax Obligations
BAS, PAYG withholding, superannuation and income tax obligations can create significant cash outflows.
These payments should not come as a surprise. Staying on top of your BAS lodgement and tax returns makes them much easier to plan for.
Including them in your 13-week forecast allows you to see the effect on your cash position several weeks in advance.
4. You Are Planning to Hire
Hiring another employee is not simply a question of whether the business can afford their weekly salary.
You may also need to consider:
- Superannuation (including whether contractors with an ABN still need super)
- Leave entitlements
- WorkCover
- Payroll tax, where applicable
- Equipment
- Software
- Training
- Recruitment costs
- Other employment overheads
Before committing to another employee, a forecast can help determine whether the business has sufficient cash capacity. Accurate payroll data makes that forecast far more reliable.
5. You Are Considering a Major Purchase
Suppose your business has $150,000 in the bank and you are considering purchasing $80,000 of equipment.
At first glance, the business can afford it.
But what if, over the following six weeks, you also have:
- $70,000 of wages
- $35,000 of supplier payments
- $28,000 BAS payment
- $15,000 loan repayments
while a major customer payment is delayed?
The better question is not:
“Do we have enough money today?”
It is:
“What will our cash position look like after we make this decision?”
That is exactly the type of question a 13-week forecast is designed to answer.
6. Cash Flow Is Already Tight
If you regularly find yourself:
- Delaying supplier payments
- Waiting for customer receipts before paying bills
- Using credit cards to fund normal operating expenses
- Falling behind on tax obligations
- Moving money between accounts to cover payroll
- Constantly checking the bank balance before approving payments
then the business may need more structured cash management. Better control of accounts payable can also help you time supplier payments more strategically.
At this stage, cash flow forecasting becomes much more than an accounting report.
It becomes a management tool.
The Real Benefit: Seeing the Problem Before It Happens
Consider a simplified forecast:
| Week | Forecast Closing Cash |
|---|---|
| Week 1 | $118,000 |
| Week 3 | $96,000 |
| Week 5 | $71,000 |
| Week 7 | $44,000 |
| Week 9 | $18,000 |
| Week 11 | ($12,000) |
| Week 13 | $9,000 |
Without a forecast, management may not realise there is a problem until Week 10 or Week 11.
With a forecast, management can potentially see the cash shortfall months earlier.
That creates time to consider appropriate actions.
Depending on the circumstances, this could include:
- Following up overdue customers earlier
- Reviewing payment terms
- Renegotiating supplier payment timing
- Delaying non-essential expenditure
- Reviewing inventory purchases
- Adjusting the timing of capital expenditure
- Reviewing owner drawings
- Arranging appropriate working capital facilities
The purpose is not simply to predict a problem.
It is to give management time to make better decisions.
A 13-Week Forecast Should Be Rolling
A useful cash flow forecast should not be prepared once and then forgotten.
Ideally, it becomes a rolling 13-week forecast.
At the end of each week:
- Replace the forecast for that week with actual results.
- Review differences between forecast and actual cash movements.
- Update assumptions for the remaining weeks.
- Add a new Week 13.
This means management always has approximately three months of forward visibility. Keeping your books current through regular bookkeeping and well-configured accounting software makes the weekly update quick and accurate.
Forecast vs Actual: Where the Real Insight Begins
One of the most valuable parts of forecasting is comparing what you expected to happen with what actually happened.
For example:
Expected customer collections: $100,000
Actual collections: $72,000
Variance: $28,000 unfavourable
Management can then ask:
Why?
Was a major customer late?
Were sales lower than expected?
Were invoices sent late?
Is the debtor collection process ineffective?
Were the forecast assumptions unrealistic?
This process turns a spreadsheet into a genuine management conversation.
Scenario Planning Makes the Forecast Even More Valuable
Growing businesses rarely operate exactly according to plan.
That is why a good forecast can include different scenarios.
Base Case
What management reasonably expects to happen.
Downside Case
What happens if:
- Customers pay more slowly
- Sales decline
- Supplier costs increase
- An unexpected expense occurs
Growth Case
What happens if:
- You win a major contract
- Hire additional employees
- Purchase more inventory
- Invest in equipment
Scenario planning helps management understand the financial consequences before making the decision.
What a 13-Week Forecast Cannot Do
A forecast is not a guarantee.
It is based on assumptions, and actual results will inevitably differ.
Its value comes from making those assumptions visible and regularly updating them as circumstances change.
The objective is not to predict the future perfectly.
The objective is to identify potential problems early enough to do something about them.
From Looking Backwards to Looking Forward
Traditional accounting reports are essential, but they primarily tell you what has already happened.
Your Profit & Loss tells you how the business performed.
Your Balance Sheet tells you what the business owns and owes.
A cash flow forecast asks:
What is likely to happen next?
For a growing business, all three perspectives matter.
Good financial management should not only explain last month’s results. It should help management make decisions about next month, next quarter and beyond.
Is It Time for Your Business to Start Forecasting?
If your business is growing, cash flow is becoming harder to manage, or major financial decisions are being made based primarily on the current bank balance, a 13-week cash flow forecast may provide valuable visibility.
Instead of discovering a cash problem when it arrives, forecasting allows you to potentially identify it weeks in advance.
And that changes the conversation from:
“How are we going to pay this?”
to:
“We can see this coming — what should we do now?”
That is the real value of forward-looking financial management.
Need Better Visibility Over Your Numbers?
At Elite Plus Accounting, we help growing businesses understand more than just what happened last month.
Through our management reports and Virtual CFO services, we can assist with:
- Cash flow forecasting
- Budgets and forecasts
- Management reporting
- Scenario analysis
- KPI monitoring
- Financial performance reviews
- Forward-looking business insights
If your business is profitable but cash always seems tight, it may be time to start looking further ahead. Contact our team to get started.
Elite Plus Accounting
From Chaos to Clarity.
📞 1300 744 733
🌐 eliteplusaccounting.com.au
✉️ info@eliteplusaccounting.com.au
get in touch
Connect with Our Experts
Our dedicated team of accountants and bookkeepers is here to guide you toward the best financial solutions. Reach out today and speak with one of our experienced professionals to get started on the right path.


Recent Blogs
A 13-week cash flow forecast helps growing businesses identify potential cash shortages, plan upcoming expenses, manage working capital, and make informed financial decisions before problems arise.
Read More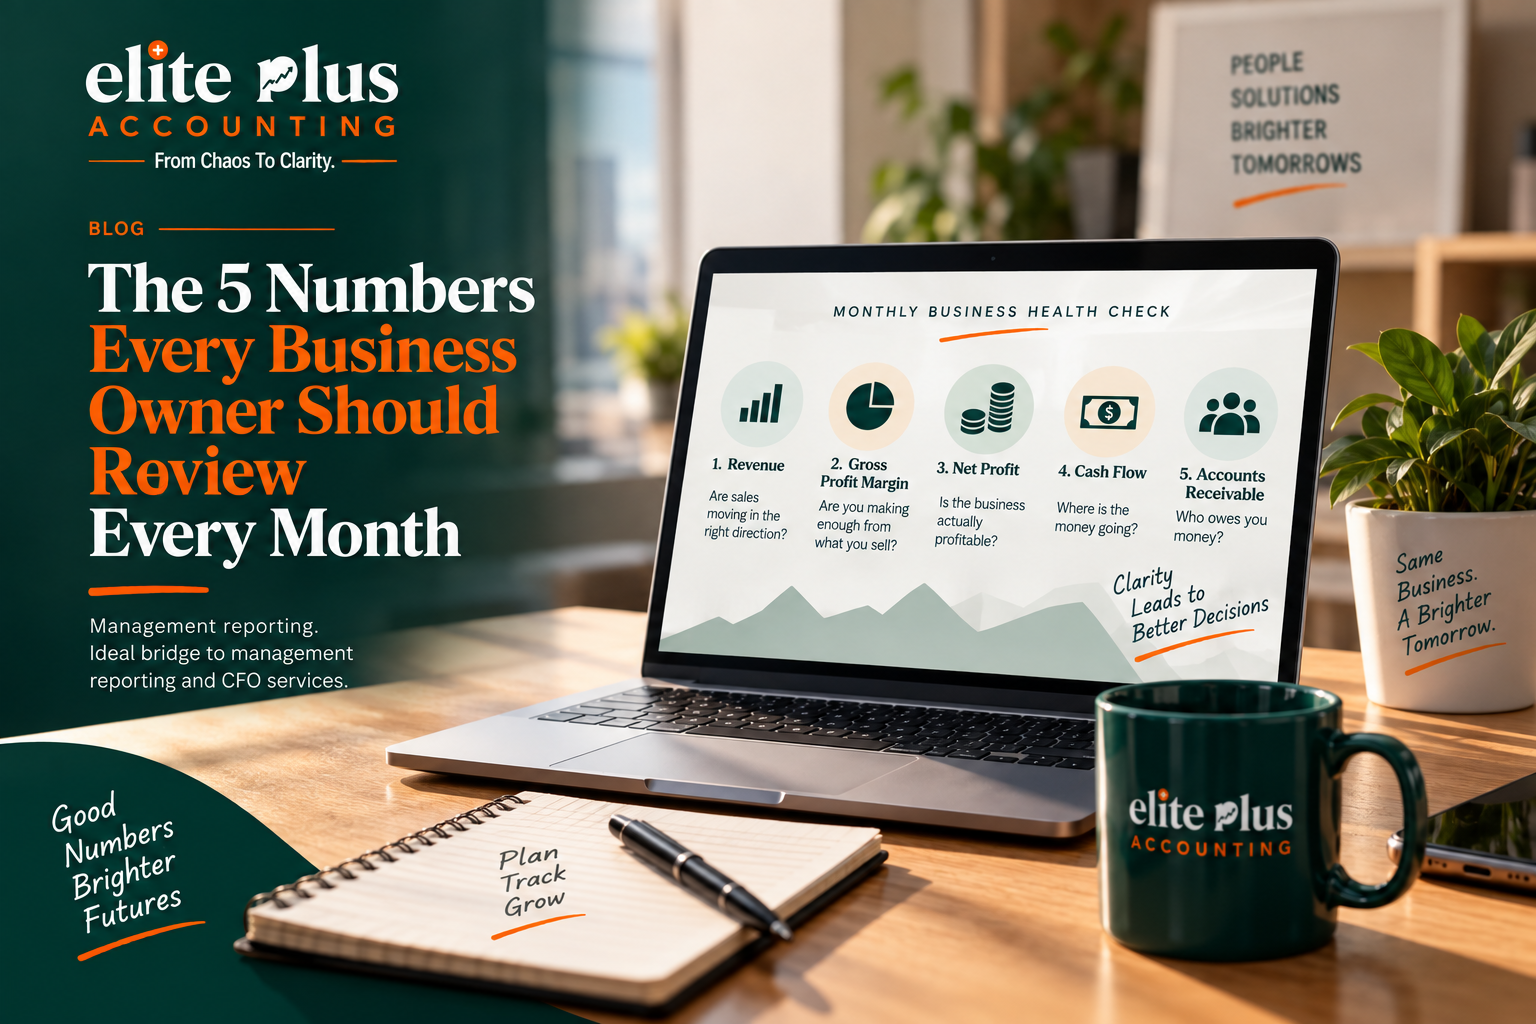
Learn the five key numbers every business owner should review monthly to understand financial performance, manage cash flow, identify issues early, and make better business decisions.
Read More
A common assumption among Australian business owners is: “They have an ABN and send me an invoice, so they are responsible for their own super.” Unfortunately, it is not always that simple. For super guarantee purposes, the ATO looks at the substance of the arrangement. Some independent contractors must still receive super where the contract is wholly […]
Read More